Commercial Real Estate Lending Is Splitting in Two—and Boise Investors Should Pay Attention
Commercial real estate financing is sending two very different messages right now.
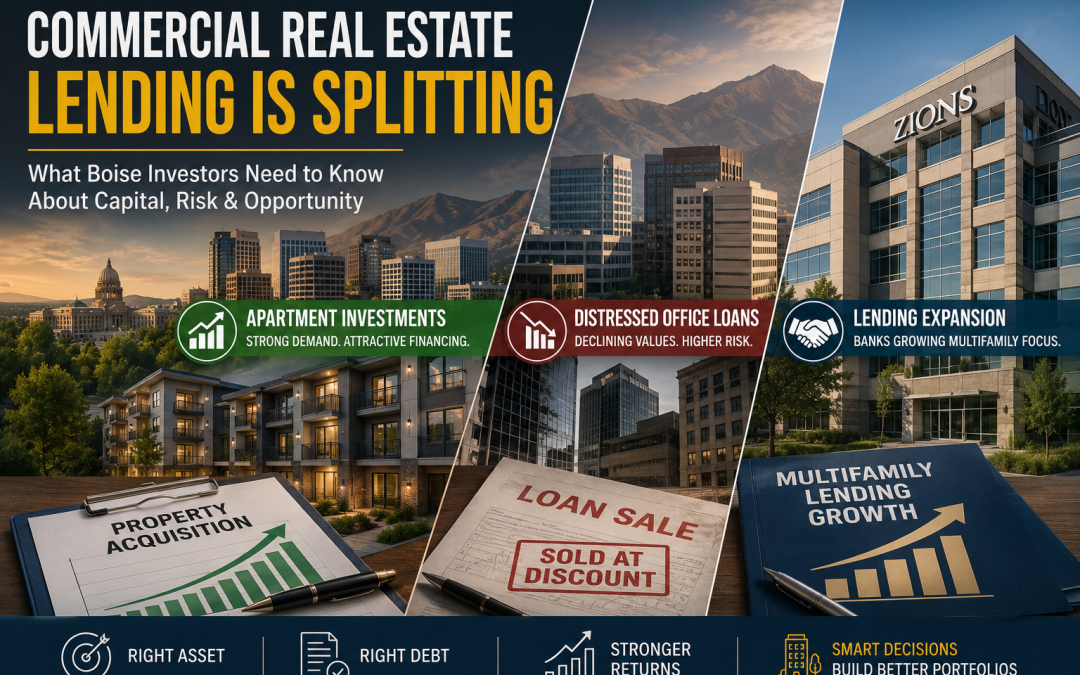
Lenders are putting serious money behind apartment acquisitions, while troubled office properties can still suffer enormous losses. At the same time, major banks are expanding their multifamily lending platforms.
For Boise commercial real estate investors, that divide matters. Capital hasn’t disappeared from the market. It has become much more selective about where it wants to go.
According to reporting by Mark Heschmeyer of CoStar News, recent transactions involving apartments in Texas, a distressed office complex in Pittsburgh and Zions Bancorporation’s expansion into multifamily lending show how differently lenders and investors are treating property types today. The original CoStar News article provides the underlying financing and transaction details.
For Boise investors, developers and property owners, there are several important lessons hiding inside these national deals.
Multifamily Is Still Attracting Big Capital
One of the clearest signals comes from Texas.
Strategic Value Partners and Spirit Investment Partners acquired two recently built apartment properties totaling 895 units in Houston and Denton.
The purchase price was approximately $139 million, or about $155,000 per apartment.
To complete the acquisition, the buyers combined roughly $101.6 million in debt with $40 million in equity.
That’s meaningful leverage for properties that aren’t fully stabilized.
The Houston property, Resia Ten Oaks, contains 573 units and was approximately 73% occupied as of July. The 322-unit Denton property was more than 92% leased.
Combined occupancy was just under 80%.
In other words, lenders were willing to finance a significant portion of the acquisition even though the portfolio still had lease-up risk.
Why?
The investors see an opportunity to improve performance as occupancy increases and concessions are reduced.
That’s a classic value-add strategy: buy quality real estate during a period of temporary weakness, stabilize it and capture the upside.
What Boise Multifamily Investors Can Learn From Texas
There is an important lesson here for Boise multifamily real estate.
Occupancy alone doesn’t determine whether a property is financeable.
Lenders and sophisticated investors look at the entire story:
- Replacement cost
- Location
- Age and condition
- Rent growth potential
- Concessions
- Supply pipeline
- Population growth
- Stabilized cash flow
- Sponsor experience
- Exit value
A newer apartment project struggling through lease-up can be very different from an older property losing tenants because demand has disappeared.
That’s especially relevant in growing markets.
Boise, Meridian, Nampa and Caldwell have added significant multifamily inventory over the past several years. When multiple projects deliver around the same time, concessions can increase and occupancy can temporarily soften.
That doesn’t automatically mean the long-term investment thesis is broken.
It may simply mean the market needs time to absorb the new units.
For investors with patient capital, temporary lease-up pressure can create acquisition opportunities.
Office Real Estate Is Telling a Different Story
Now compare the Texas apartment transaction with Pittsburgh.
A loan tied to Gateway Center, a four-building downtown office complex totaling nearly 1.47 million square feet, was sold at a steep discount.
The original CMBS loan balance was approximately $91.8 million.
The note generated only about $37.4 million when sold.
According to CoStar’s reporting, the transaction resulted in a roughly $64.8 million loss for CMBS investors after the loan had struggled for years.
The property’s problems weren’t simply financial.
Occupancy had fallen to roughly 61%, and property cash flow had been negative for three consecutive years.
That is where commercial real estate problems can compound quickly.
Lower occupancy means lower revenue.
Lower revenue makes it harder to fund improvements.
Deferred maintenance can make leasing more difficult.
Weak leasing can push property values lower.
And lower values can make refinancing nearly impossible.
Eventually, the debt may be worth far less than its original balance.
The Boise Office Lesson: Basis Matters Again
For Boise office investors, distressed national office sales shouldn’t automatically be viewed as evidence that all office buildings are bad investments.
The better lesson is that purchase price and debt structure matter enormously.
A building bought at the wrong basis with too much leverage can become a problem quickly when vacancy rises.
But that same building purchased later at a dramatically lower price may become an entirely different investment.
This is one reason office distress can eventually create opportunity.
If an investor can acquire a building well below replacement cost, renovate it, lease it competitively and carry manageable debt, the risk profile changes.
The challenge is determining whether the building is temporarily distressed or fundamentally obsolete.
That distinction will matter in Downtown Boise commercial real estate and throughout the Treasure Valley.
Some older office buildings may need significant investment to remain competitive.
Others may have excellent locations, parking and layouts but simply need cosmetic improvements and a lower cost basis.
The building isn’t always the problem.
Sometimes the basis is.
Zions Makes a Big Bet on Apartment Lending
The third development may be particularly interesting for Idaho investors because it involves Salt Lake City-based Zions Bancorporation.
Zions acquired the multifamily lending operation of Basis Multifamily Finance I, expanding the bank’s ability to originate apartment loans through Fannie Mae and Freddie Mac programs.
The acquisition gives Zions an established lending team, origination platform and servicing capabilities.
That’s significant because Fannie Mae and Freddie Mac remain major sources of long-term financing for apartment properties.
Zions has already been increasing its exposure to the sector.
According to FDIC data cited by CoStar, the bank’s multifamily loan portfolio increased from approximately $2.92 billion at the end of 2024 to $3.22 billion by the end of 2025.
Loan performance has also remained strong, with relatively little of the portfolio reported as delinquent.
This isn’t a lender pulling away from commercial real estate.
It’s a lender deciding where it wants more exposure.
And right now, apartments remain attractive.
Capital Is Available—But It Wants the Right Story
These three transactions tell a larger story about today’s commercial real estate financing environment.
Capital is becoming more selective.
That means investors shouldn’t simply ask:
“Can I get financing?”
A better question is:
“What kind of real estate are lenders actively trying to finance?”
There is a big difference.
Apartment properties with durable housing demand can still attract aggressive financing.
High-quality industrial properties remain desirable to many lenders.
Well-located retail with strong tenants can finance well.
But challenged office buildings with high vacancy, weak cash flow and major capital needs can face a completely different lending environment.
That gap can influence property values throughout the market.
What This Could Mean for Boise Development
Financing conditions eventually influence what gets built.
If lenders favor multifamily projects while remaining cautious about speculative office development, developers naturally follow the capital.
That can affect the future supply of Boise commercial real estate.
Apartment development may continue attracting capital when projects have strong locations and realistic underwriting.
Office construction, meanwhile, may remain limited unless a project has significant preleasing or an unusually strong sponsor.
Over time, that could create an interesting situation.
Too much apartment construction could increase competition among landlords.
Very little office construction could eventually tighten the supply of modern, high-quality office space.
Commercial real estate cycles often work that way.
Capital flows toward what looks safest until enough supply gets built to change the equation.
Local Insight: Watch the Debt Before You Watch the Cap Rate
Investors often start by asking about the cap rate.
Today, I would spend just as much time looking at the debt.
Interest rate, amortization, maturity date, loan-to-value ratio and extension options can dramatically affect investment performance.
A good property with bad debt can become a bad investment.
A challenged property with conservative debt and a low purchase basis can become an opportunity.
For Boise investment property, I would pay particular attention to:
- Current versus stabilized net operating income
- Existing loan maturity
- Cost of replacement financing
- Required equity
- Interest-only periods
- Loan extension requirements
- Capital improvement needs
- Tenant rollover
- Replacement cost
- Downside value
That final point is increasingly important.
Ask what the property is worth if your optimistic assumptions don’t happen.
That’s often more useful than calculating the best-case return.
My Take
The commercial real estate capital markets aren’t closed.
They’re sorting winners from losers.
The Texas apartment acquisition shows that lenders will still provide substantial financing when they believe there is a credible path to stabilization.
The Pittsburgh office situation shows what can happen when occupancy, cash flow and property value deteriorate while debt remains outstanding.
And Zions’ expansion into apartment lending shows that some financial institutions aren’t retreating from real estate—they’re strategically increasing exposure to sectors they believe offer attractive risk-adjusted returns.
For Boise commercial real estate investors, that’s the key takeaway.
Don’t treat “commercial real estate lending” as one market.
A multifamily property in Meridian, an industrial building in Nampa, a neighborhood retail center in Boise and an older downtown office building can face completely different financing environments.
The investors who understand where capital wants to go—and structure their acquisitions accordingly—may have a significant advantage over the next several years.
Because in this market, finding the property is only half the deal.
The other half is finding the capital that believes in it.
Mike Gioioso (joy-OH-so) has for 16+ years been helping companies of all sizes buy, build, and lease perfect places for business in greater Boise, Idaho and beyond.
www.streetsmartidaho.com mike@streetsmartidaho.com 208-209-9166
Tags: #boisecommercialrealestate, #boiserealestate, #boiseinvestmentproperty, #boisecommercialrealestateinvestment, #boisecommerciallending, #boisecommercialrealestatefinancing, #commercialrealestateloans, #commercialrealestatelending, #crefinancing, #crelending, #boisemultifamily, #boisemultifamilyrealestate, #boiseapartmentinvestment, #boiseapartments, #boisemultifamilyinvestment