What National CMBS Trends Could Mean for Boise Commercial Real Estate
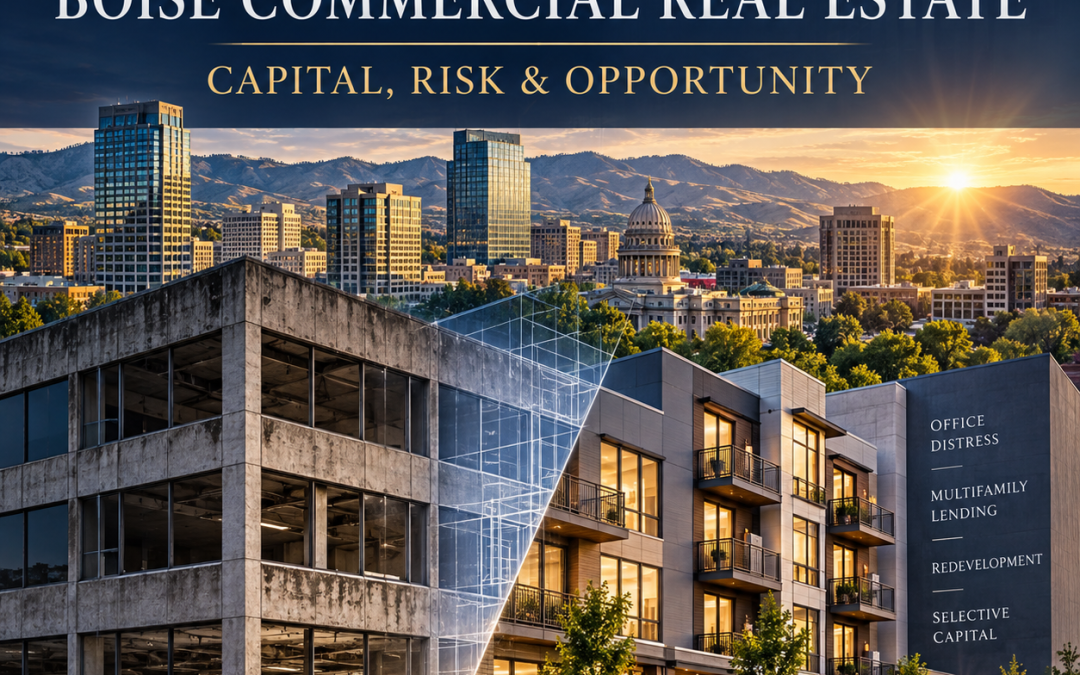
Commercial real estate’s next chapter is being shaped by three powerful forces: aging office properties, renewed lending activity, and a growing preference for assets backed by strong tenants.
These national trends may seem far removed from Idaho, but they carry important lessons for Boise commercial real estate investors, landlords, tenants, and developers.
According to reporting by Mark Heschmeyer in CoStar News, recent activity in the commercial mortgage-backed securities market highlights both the risks facing older office properties and the continued flow of capital toward multifamily and well-leased commercial assets.
Older Office Properties Need a New Story
Constitution Plaza in downtown Hartford, Connecticut, shows how quickly an office investment can lose value when occupancy falls, leases expire, and refinancing becomes difficult.
The six-building complex covers 6.6 acres and was valued at $94.4 million when its loan was originated. A February appraisal placed its value at only $13 million, representing an estimated decline of about 86%.
The property’s $43.1 million loan entered special servicing in 2023 after it was not repaid at maturity. Occupancy has fallen to roughly the low-60% range, and the property generates only about 57 cents of operating income for every dollar of debt payments.
Its outlook could become even more difficult:
- Approximately 37% of the rentable space is scheduled to expire within one year.
- Another 52% could roll during the following two years.
- One of the largest tenants has already reduced its space.
- A future tenant departure could push occupancy below 50%.
Instead of continuing to market the property only as an office campus, the brokerage team is presenting it as a redevelopment opportunity. Hartford has already converted several underused downtown office buildings into apartments, giving investors a possible path forward.
Why This Matters in Boise
Boise is not Hartford, and our office market has different supply, employment, and growth patterns. Still, the broader lesson applies here.
Older office buildings cannot rely on yesterday’s value assumptions. Buyers and lenders are paying closer attention to:
- Upcoming lease expirations
- Tenant concentration
- Building condition
- Cost of improvements
- Debt-service coverage
- Alternative uses
- The amount of new equity required at refinancing
In Boise office leasing, buildings with modern interiors, flexible layouts, strong parking, good visibility, and nearby services have a better chance of attracting tenants. Properties that lack those features may need aggressive pricing, renovation, or a different use.
Not every struggling office property will work as housing. Zoning, floor depth, window placement, plumbing, parking, and construction costs can make a conversion difficult. However, owners should examine redevelopment options before vacancy becomes a larger problem.
Multifamily Continues to Attract Capital
While some office loans remain under pressure, commercial real estate collateralized loan obligation activity has accelerated.
Lenders priced approximately $25.12 billion in new CRE CLO transactions during the first half of 2026, according to Morningstar DBRS data cited by CoStar. If the pace continues, annual volume could exceed 2025 and move close to previous records.
Apartment loans accounted for 83% of second-quarter issuance. The largest transaction of the quarter was a $1.5 billion pool backed entirely by multifamily loans.
Industrial properties also gained market share over the previous year, becoming the second-largest property category in the market. That suggests lenders are gradually becoming more comfortable with selected industrial and hotel loans, although apartments remain the clear favorite.
Multifamily is not free from financial stress. Apartment properties represented 71% of loans in special servicing during the quarter. However, several performance measures improved:
- Multifamily delinquencies declined from 5.8% to 4.9%.
- The special-servicing rate fell from 5.4% to 4.5%.
- The balance of specially serviced apartment debt decreased by approximately $370 million.
Boise Investment and Development Impact
For Boise development and investment property decisions, this activity shows that capital is available—but it is selective.
Lenders continue to like housing because people need places to live and apartment income is spread across many tenants. One vacancy normally does not create the same level of risk as losing a major office tenant.
That does not mean every Boise-area apartment project will receive favorable financing. New developments must still support their rents, construction costs, operating assumptions, and lease-up schedule. Projects in Boise, Meridian, Nampa, Caldwell, and other growing Treasure Valley communities will be evaluated based on their specific submarket rather than regional population growth alone.
Investors should pay close attention to:
- Current rents compared with projected rents
- Competing units under construction
- Insurance and property-tax increases
- Concessions needed to attract residents
- Interest-rate protection
- Loan maturity and refinancing risk
The market appears willing to finance quality multifamily assets, but lenders are demanding realistic numbers.
Strong Leases Can Still Unlock Office Financing
A separate transaction covered by CoStar provides a sharp contrast to the Hartford property.
Two neighboring office towers in Bellevue, Washington, received a $210 million refinancing. The buildings total approximately 543,000 square feet and are fully leased to Meta through 2033.
The leases are structured on a triple-net basis, placing responsibility for property taxes, insurance, and maintenance costs on the tenant. Goldman Sachs originated the fixed-rate, interest-only mortgage.
Grandbridge Real Estate Capital was selected as master servicer for the transaction. This is the company’s first CMBS master-servicing assignment and comes after it launched the business line in June.
A master servicer manages the regular administration of performing CMBS loans. That includes collecting payments, monitoring the loan, maintaining escrow accounts, distributing funds, and moving a troubled loan to a special servicer when necessary.
For the broader office market, the Bellevue refinancing makes one point especially clear: lenders have not completely abandoned office properties. They are willing to finance assets that offer dependable income, long lease terms, credible tenants, and a clear repayment path.
My Take: The Market Is Dividing by Quality
The commercial real estate market is not moving in one direction. Instead, the gap between strong and weak properties is getting wider.
A fully leased building with long-term income may still attract significant financing. An older building with declining occupancy and several near-term lease expirations may struggle to refinance at almost any previous valuation.
That divide matters for Boise commercial real estate.
Landlords should begin lease-renewal discussions well before expiration dates. Waiting until the final months of a lease can leave an owner with fewer choices and weaker negotiating power.
Tenants may find opportunities in older buildings, especially if they can secure improvement allowances, favorable rental rates, signage, or flexible renewal terms. However, tenants should also consider whether the landlord has enough capital to maintain and improve the property.
Investors need to underwrite more than the current rent roll. They should model tenant departures, improvement costs, leasing commissions, free rent, higher interest rates, and longer vacancy periods.
Developers should also watch for properties where the land or redevelopment potential may eventually be worth more than the existing building. In some cases, the best value may come from changing the property’s use rather than trying to preserve an outdated layout.
The central message is simple: capital remains available, but certainty commands a premium. Strong tenancy, durable income, flexible real estate, and realistic underwriting will separate the best opportunities from the properties that continue to lose value.
Mike Gioioso (joy-OH-so) has for 16+ years been helping companies of all sizes buy, build, and lease perfect places for business in greater Boise, Idaho and beyond.
www.streetsmartidaho.com mike@streetsmartidaho.com 208-209-9166
Tags: #boisecommercialrealestate, #boiserealestate, #treasurevalleycommercialrealestate, #idahocommercialrealestate, #boiseinvestmentproperty, #boisedevelopment, #boiseofficemarket, #boiseofficespace, #officeleasingboise, #retailleasingboise, #boisemultifamilyrealestate, #multifamilyinvesting, #apartmentdevelopmentboise, #commercialrealestatefinancing, #cmbslending, #creclomarket